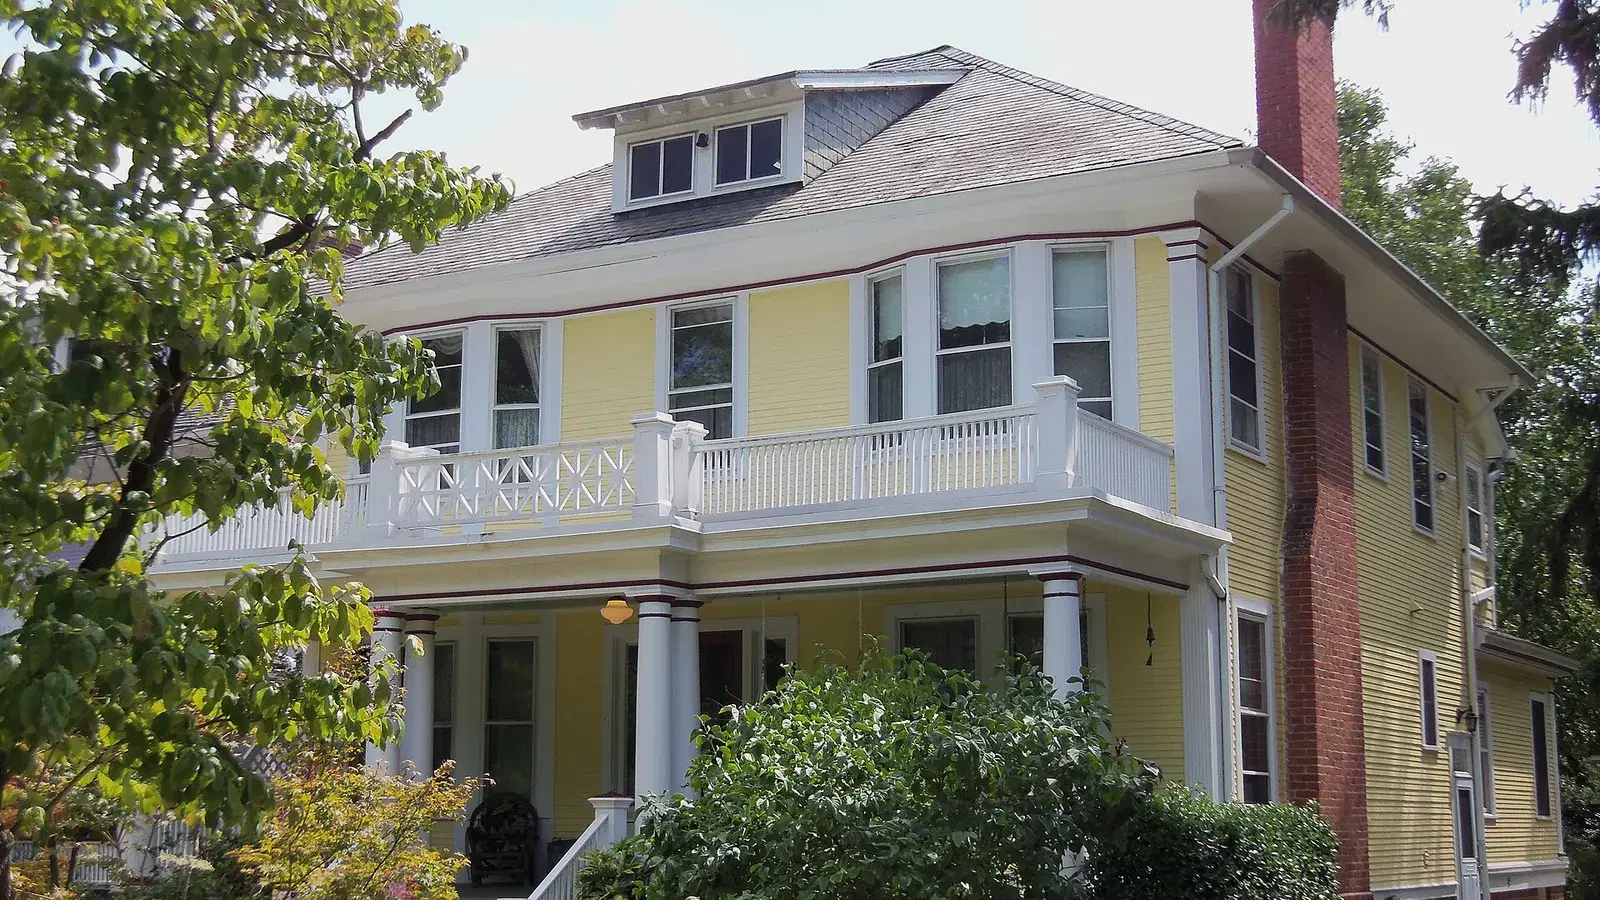
DC's most desirable neighborhoods — Capitol Hill, Logan Circle, Dupont Circle, Shaw — are filled with historic rowhouses and Victorian-era homes. Many of these properties need significant updates: modernized kitchens, updated electrical, new HVAC, or structural repairs. Renovation financing lets you roll the purchase price and rehab costs into a single mortgage.
Why Renovation Loans Make Sense in DC
A well-located but dated rowhouse on Capitol Hill might list at $750,000 and need $150,000 in renovations. Without a renovation loan, you'd need to:
- Buy the house with a traditional mortgage
- Take out a separate home equity loan or line of credit for renovations
- Or pay cash for the rehab
The problem: you can't get a home equity loan on a house you just bought with minimal equity, and few buyers have $150,000 in cash sitting around after a down payment.
Renovation loans solve this by financing the purchase price plus renovation costs in one loan, based on the home's projected after-renovation value.
FHA 203(k) Loan
How It Works
The FHA 203(k) lets you borrow up to 110% of the home's projected after-renovation appraised value, with as little as 3.5% down based on the total loan amount.
Two Versions
- Standard 203(k): For renovations over $35,000. Requires a HUD consultant to oversee the project. No maximum renovation amount (up to FHA loan limits).
- Limited 203(k): For renovations under $35,000. Simpler process, no consultant required. Good for cosmetic updates — new kitchen, bathrooms, flooring, paint.
Requirements
- Primary residence only
- 580+ credit score (3.5% down) or 500-579 (10% down)
- Licensed contractor must do the work (no DIY)
- Work must be completed within 6 months
- Property must meet FHA minimum property standards after renovation
DC-Specific Notes
- FHA loan limit in DC is $1,249,125 (2026), matching the high-cost conforming ceiling — covers most purchases, though it can be tight for large renovations on expensive properties
- Historic district rules may require specific materials or designs — factor this into your renovation budget
- The HUD consultant adds cost ($400–$1,000) but provides valuable project oversight
Conventional Renovation Loans
Fannie Mae HomeStyle Renovation
- Up to 97% LTV (3% down) for primary residences
- Loan limits track the conforming ceiling — $1,249,125 in DC for 2026
- Can be used for primary residences, second homes, and investment properties
- No HUD consultant required
- Renovation work can include luxury items (pools, landscaping) that FHA excludes
Freddie Mac CHOICERenovation
- Similar to HomeStyle with up to 97% LTV
- Includes a resilience option for weather-related improvements
- Same flexibility as HomeStyle for property types
Advantages Over FHA 203(k)
- No mortgage insurance premium after reaching 20% equity (FHA charges MIP for the life of the loan)
- More flexibility on renovation scope
- Can be used for investment properties
- No HUD consultant requirement
What Renovation Loans Cover
Typically Covered
- Kitchen and bathroom remodels
- Structural repairs (foundation, roof, framing)
- Electrical and plumbing updates
- HVAC replacement
- Flooring, painting, drywall
- Windows and doors
- Accessibility modifications
- Energy efficiency improvements
Not Covered (FHA 203(k))
- Luxury additions (swimming pools, outdoor kitchens)
- Commercial-use space
- Moving the structure to a new foundation
The Renovation Loan Process
- Get pre-approved for a renovation loan — not all lenders offer them, so find one with experience
- Find a property and make an offer contingent on renovation financing
- Get contractor bids for the planned work — you'll need detailed, itemized estimates
- Appraisal based on as-completed value — the appraiser reviews the renovation plans and estimates what the home will be worth after the work
- Close on the loan — renovation funds go into an escrow account
- Renovation begins — contractor draws funds from escrow as work progresses, with inspections at each draw
- Final inspection — once work is complete, remaining escrow funds are released
Timeline
Expect the process to take 60-90 days from contract to closing — longer than a standard purchase. Renovation work typically adds 3-6 months after closing.
Historic District Considerations
Many DC neighborhoods have historic preservation requirements:
What This Means for Your Renovation
- Exterior changes often need approval from the Historic Preservation Review Board (HPRB)
- Some materials and designs may be required (e.g., wood windows instead of vinyl)
- Required materials can add 20-40% to specific renovation costs
- Interior work is generally unrestricted
Budget Impact
Factor historic requirements into your renovation estimate from the start. A contractor experienced with DC historic properties will know what HPRB requires and can provide accurate bids.
Tips for DC Renovation Buyers
- Find a renovation-experienced lender: Not all loan officers understand 203(k) or HomeStyle loans — work with someone who has closed them before
- Get multiple contractor bids: Lenders require at least one detailed bid, but getting two or three protects your budget
- Budget a 10-15% contingency: Older homes always have surprises behind the walls
- Check the historic district overlay: Know what exterior work requires review before planning
- Consider the after-renovation value: Your loan is based on projected value — a good renovation in a strong neighborhood often creates instant equity
- Don't over-improve: The most expensive house on the block is harder to sell. Renovate to neighborhood standards, not beyond them
Renovation loans put well-located older houses back in reach — the ones most buyers scroll past because they can't picture paying for the work.