
Buy a home
Buy a home in Washington DC
Find out what you can borrow, then compare loan programs for your DC purchase.
Where to start
Three first steps for DC buyers
Estimate what you can afford, check current rates, or get pre-qualified.
What you can afford
Estimate the full monthly payment first, including property taxes, homeowners insurance, and any condo fee.
Estimate what you can afford →Current rates
Current rate examples by loan program, with the credit score, down payment, and loan amount behind each one.
See current rates →Making an offer
A pre-qualification letter shows the listing agent you can finance the purchase. Pre-qualification takes two minutes and does not pull your credit.
Get pre-qualified →DC neighborhood guides
Each guide covers one neighborhood's housing stock, price range, and financing notes.
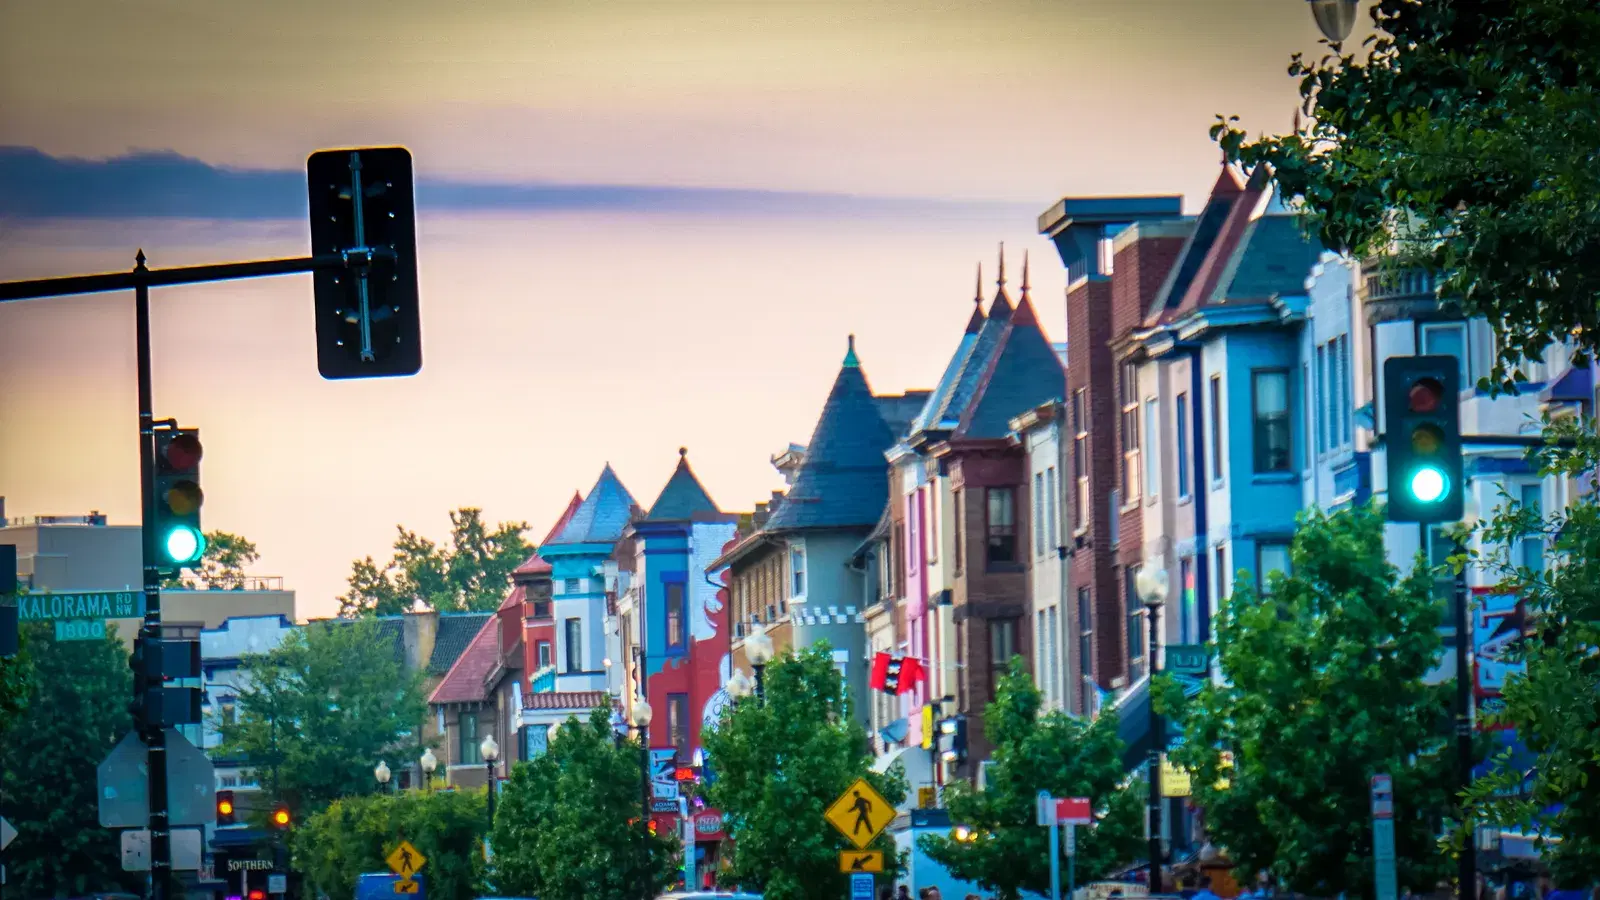 Adams Morgan & Mount Pleasant
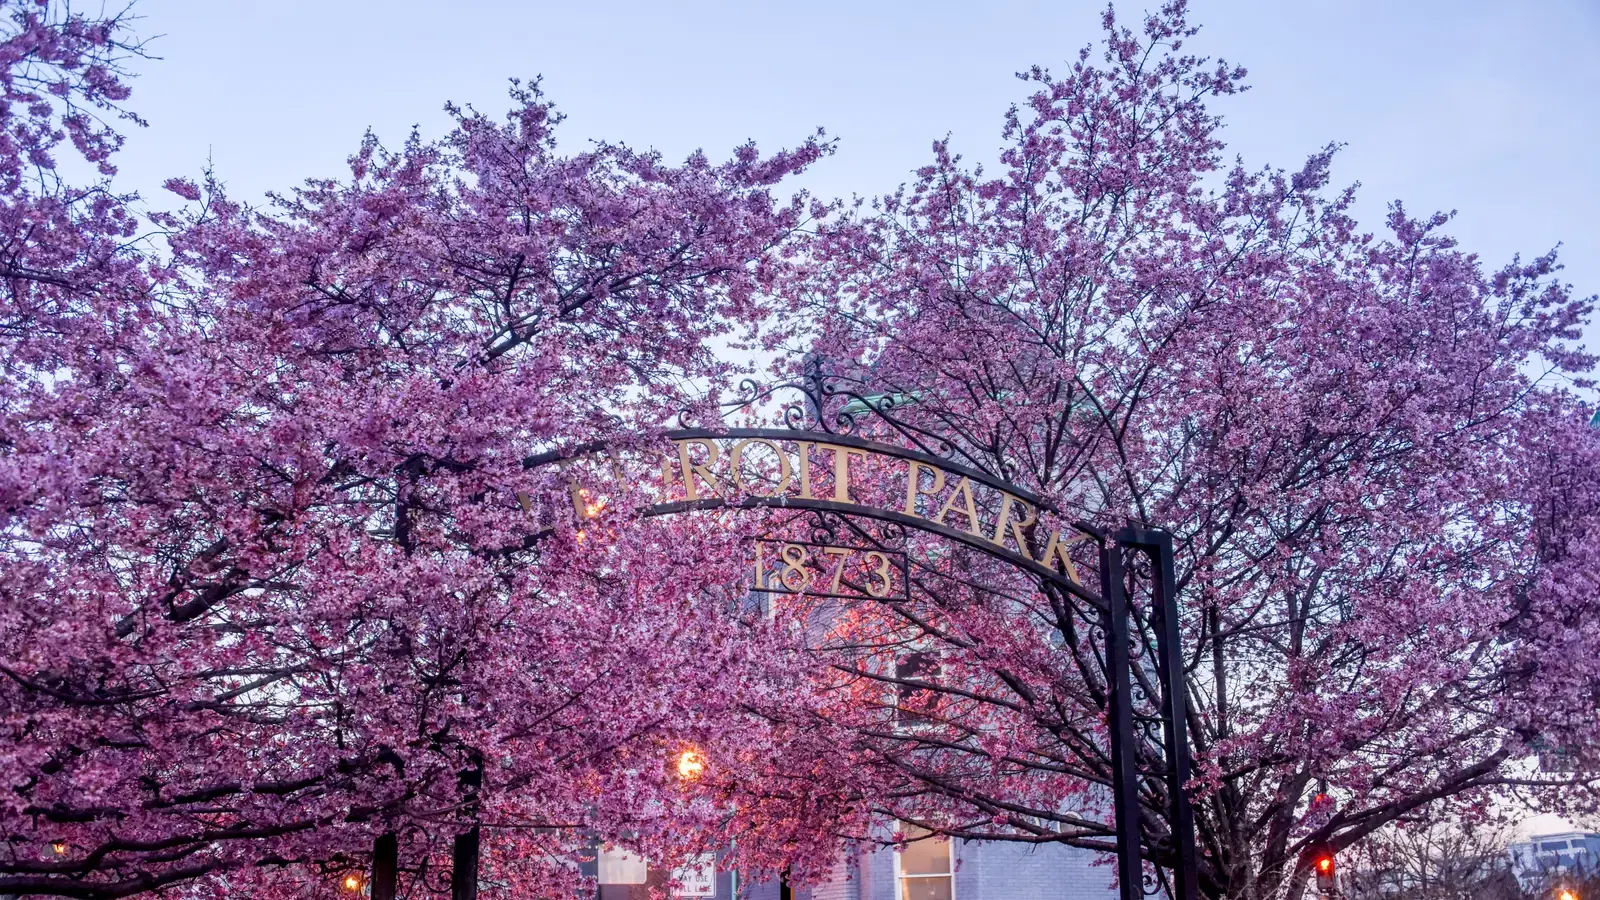 Bloomingdale & LeDroit Park
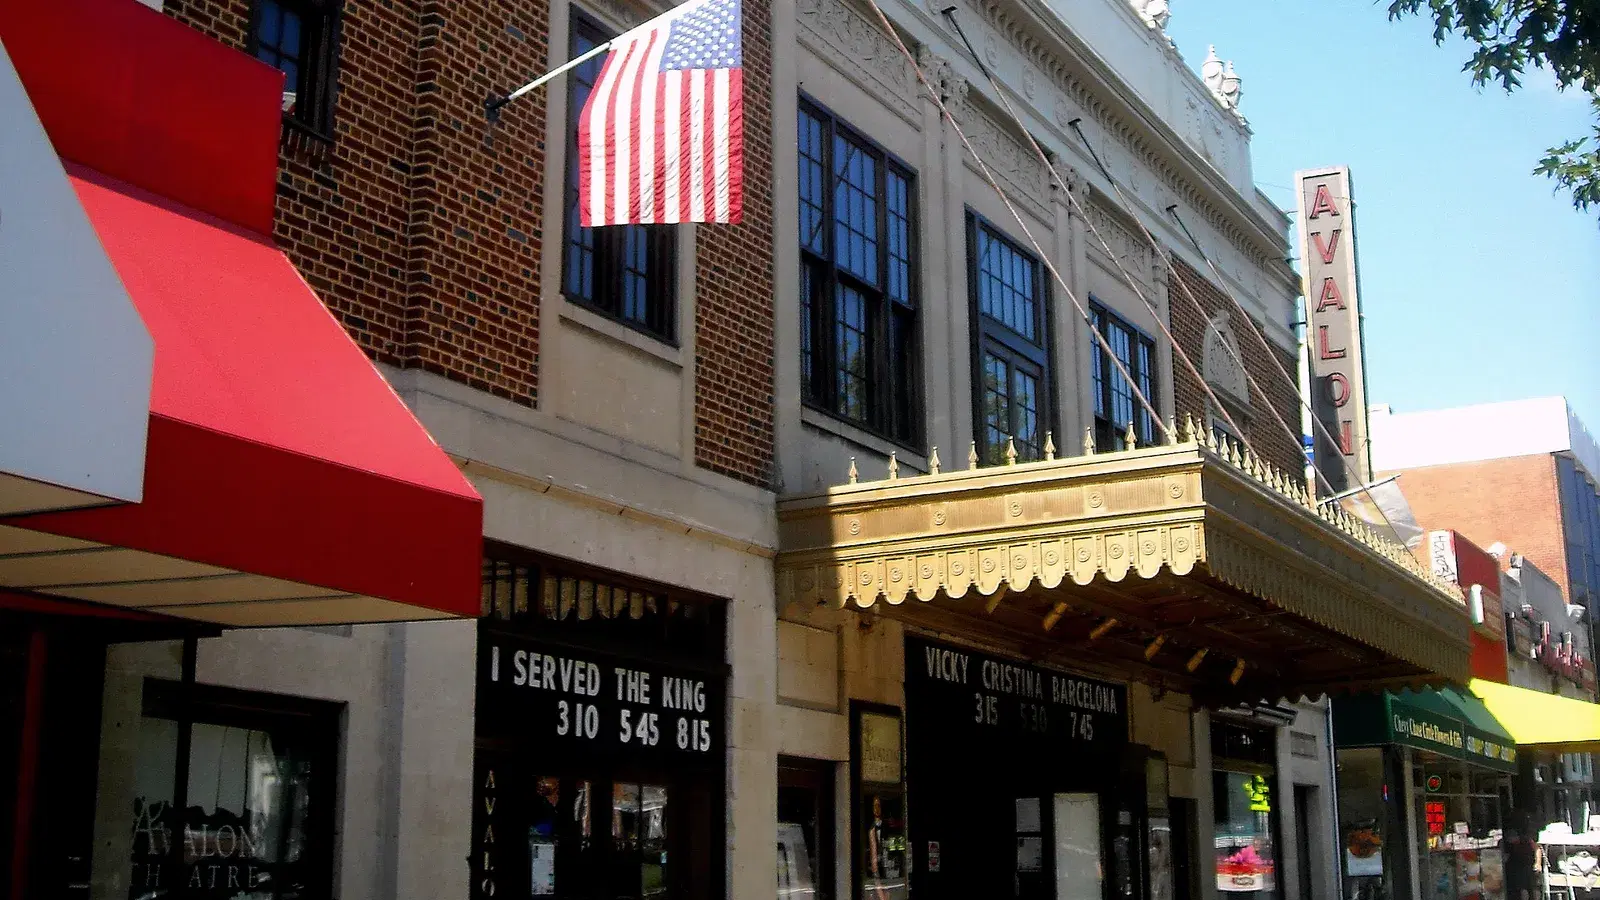 Chevy Chase DC & Upper NW
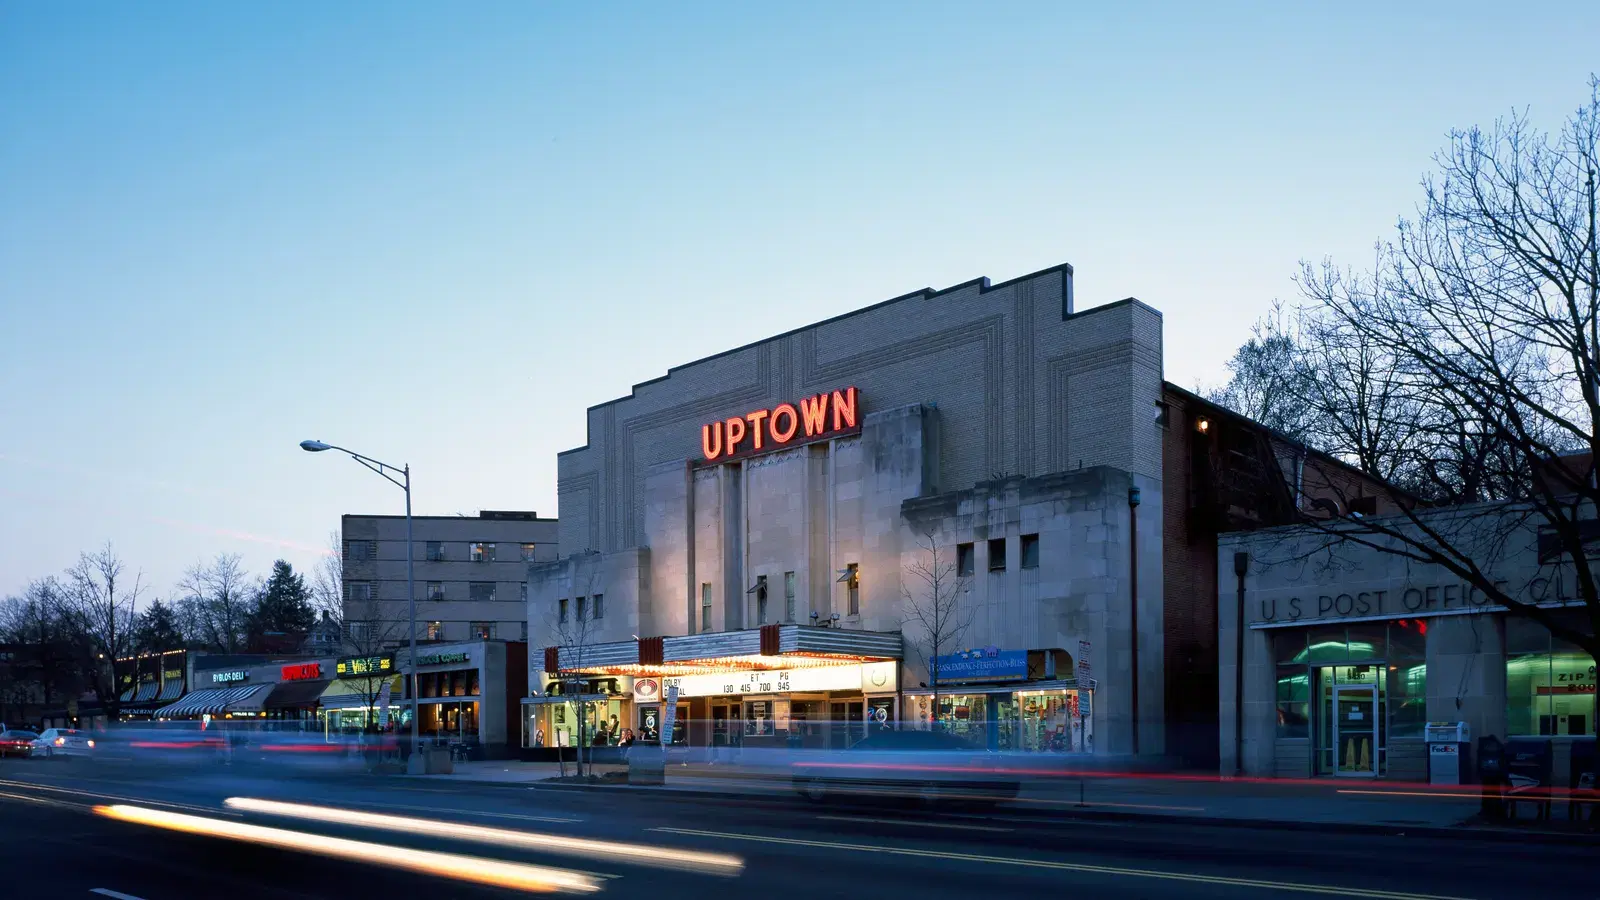 Cleveland Park
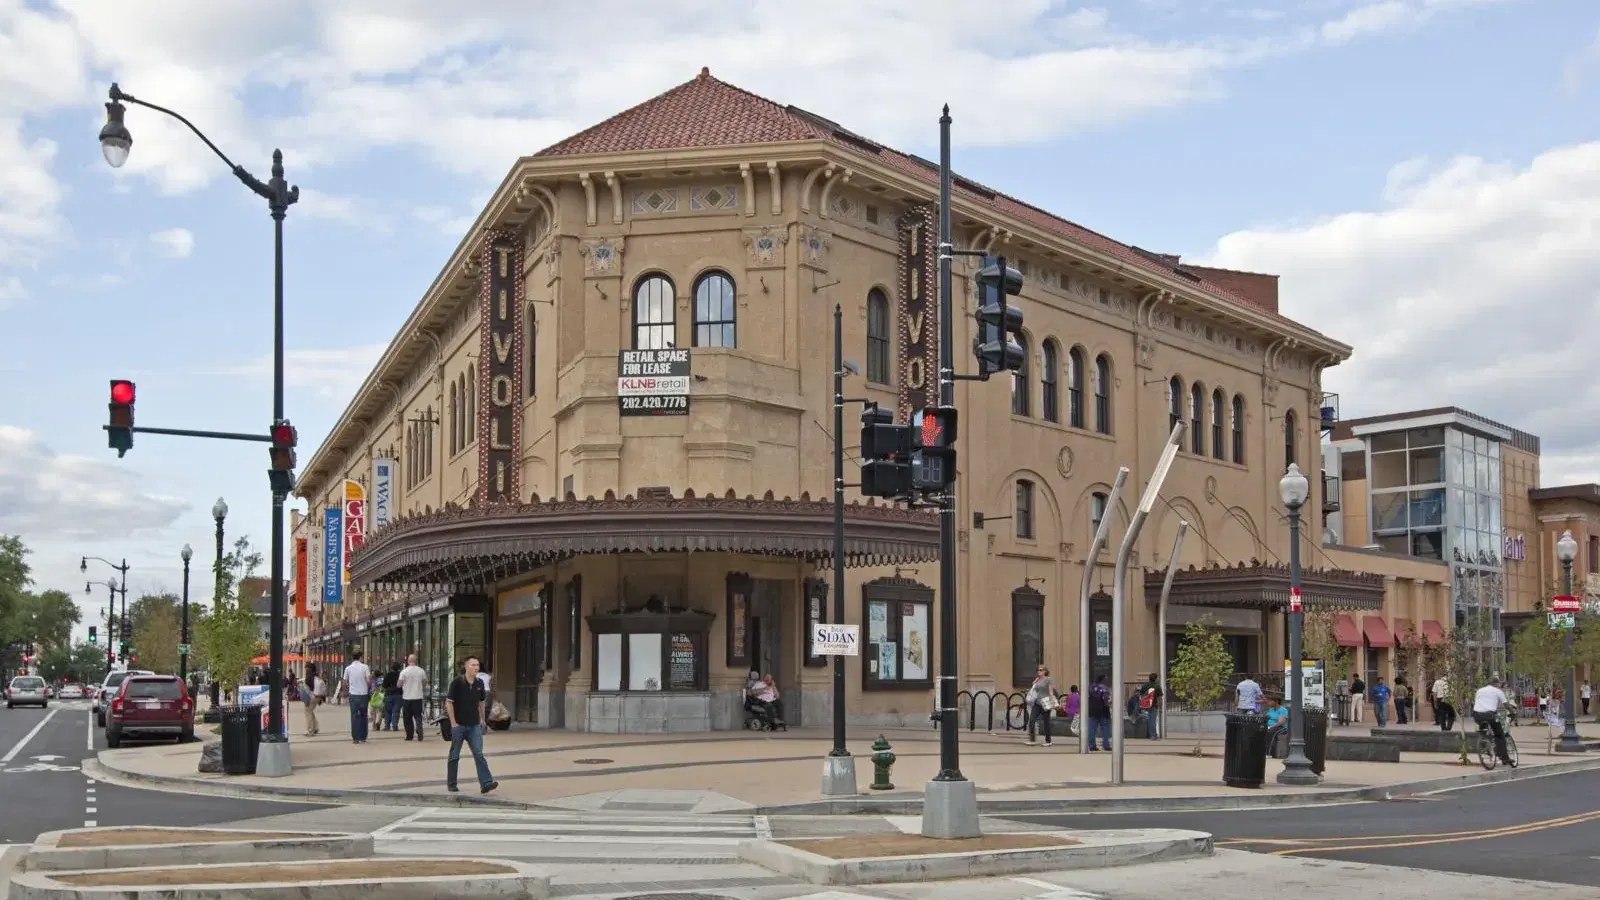 Columbia Heights
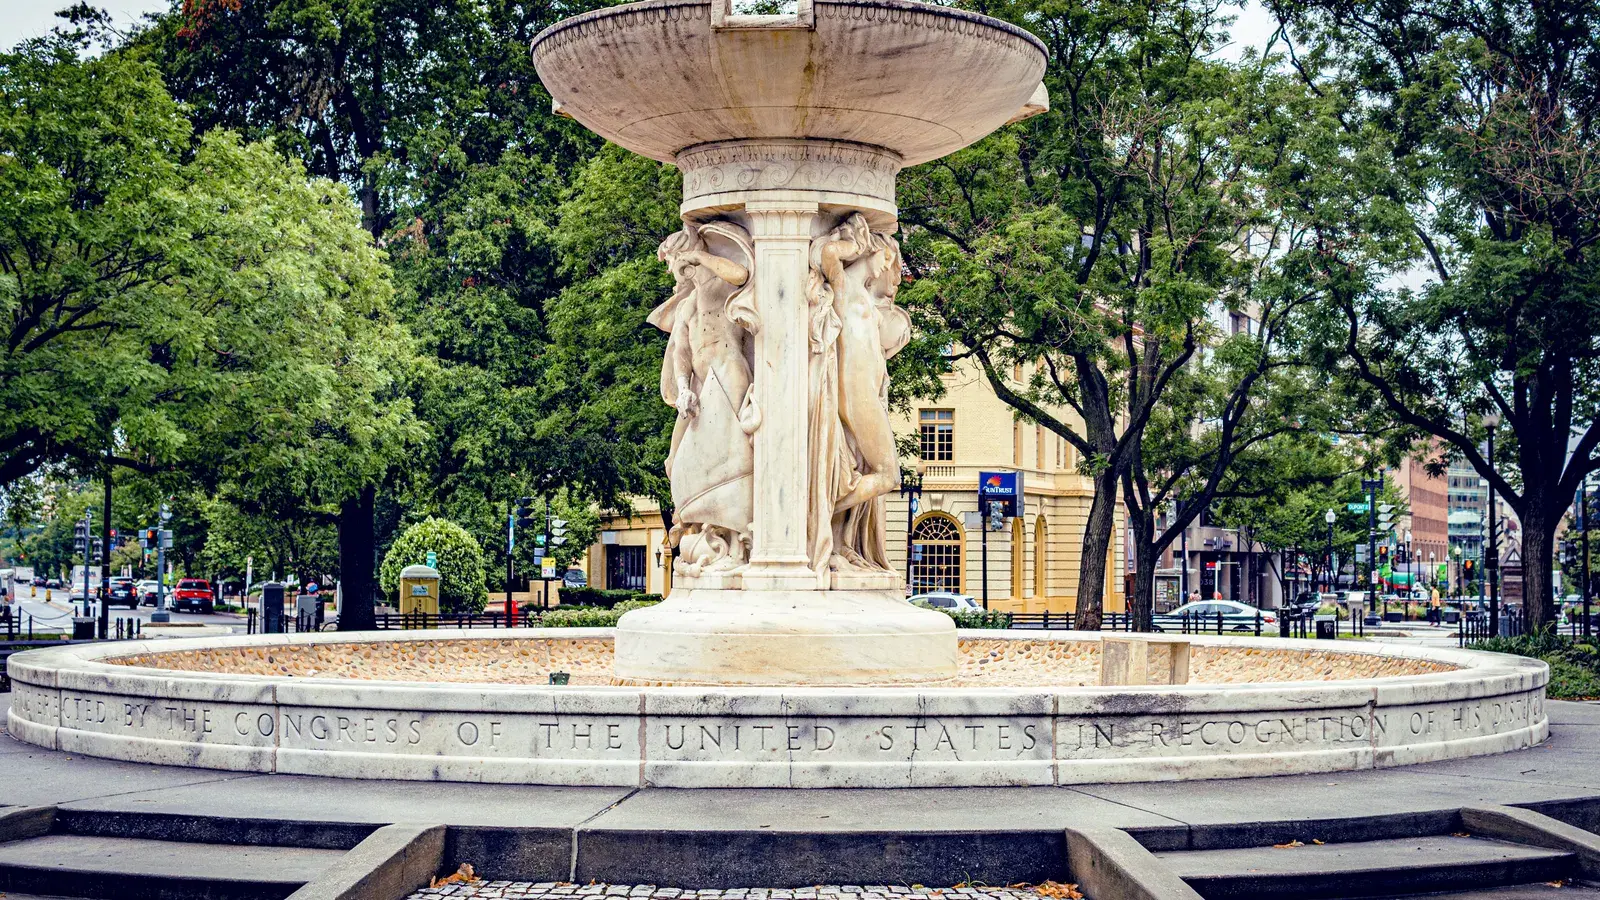 Dupont Circle & Kalorama
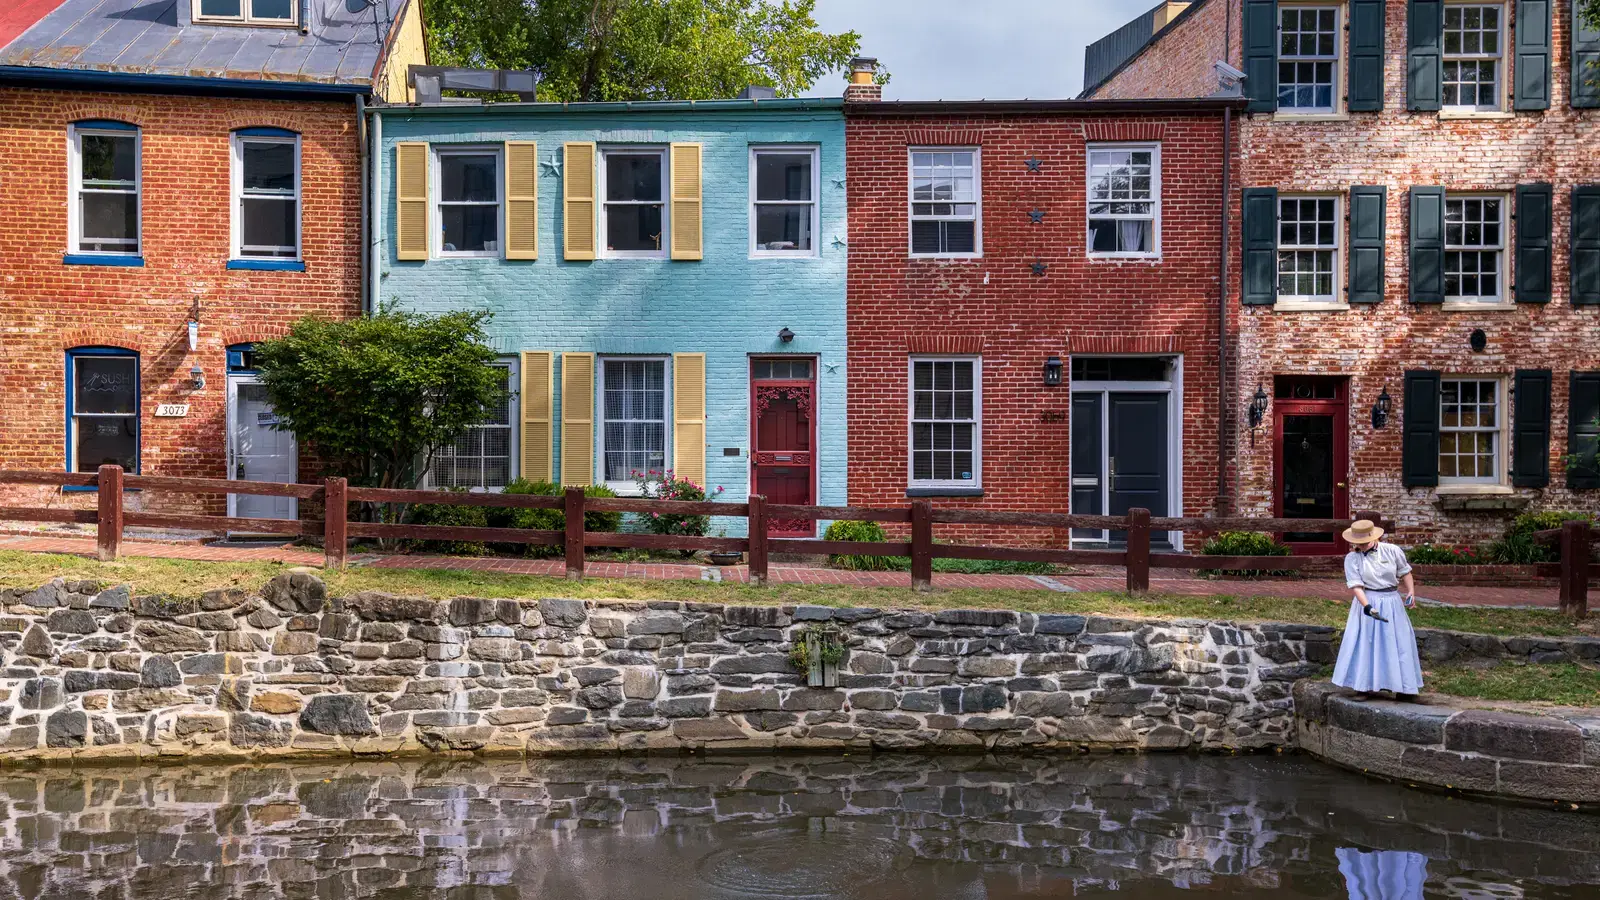 Georgetown
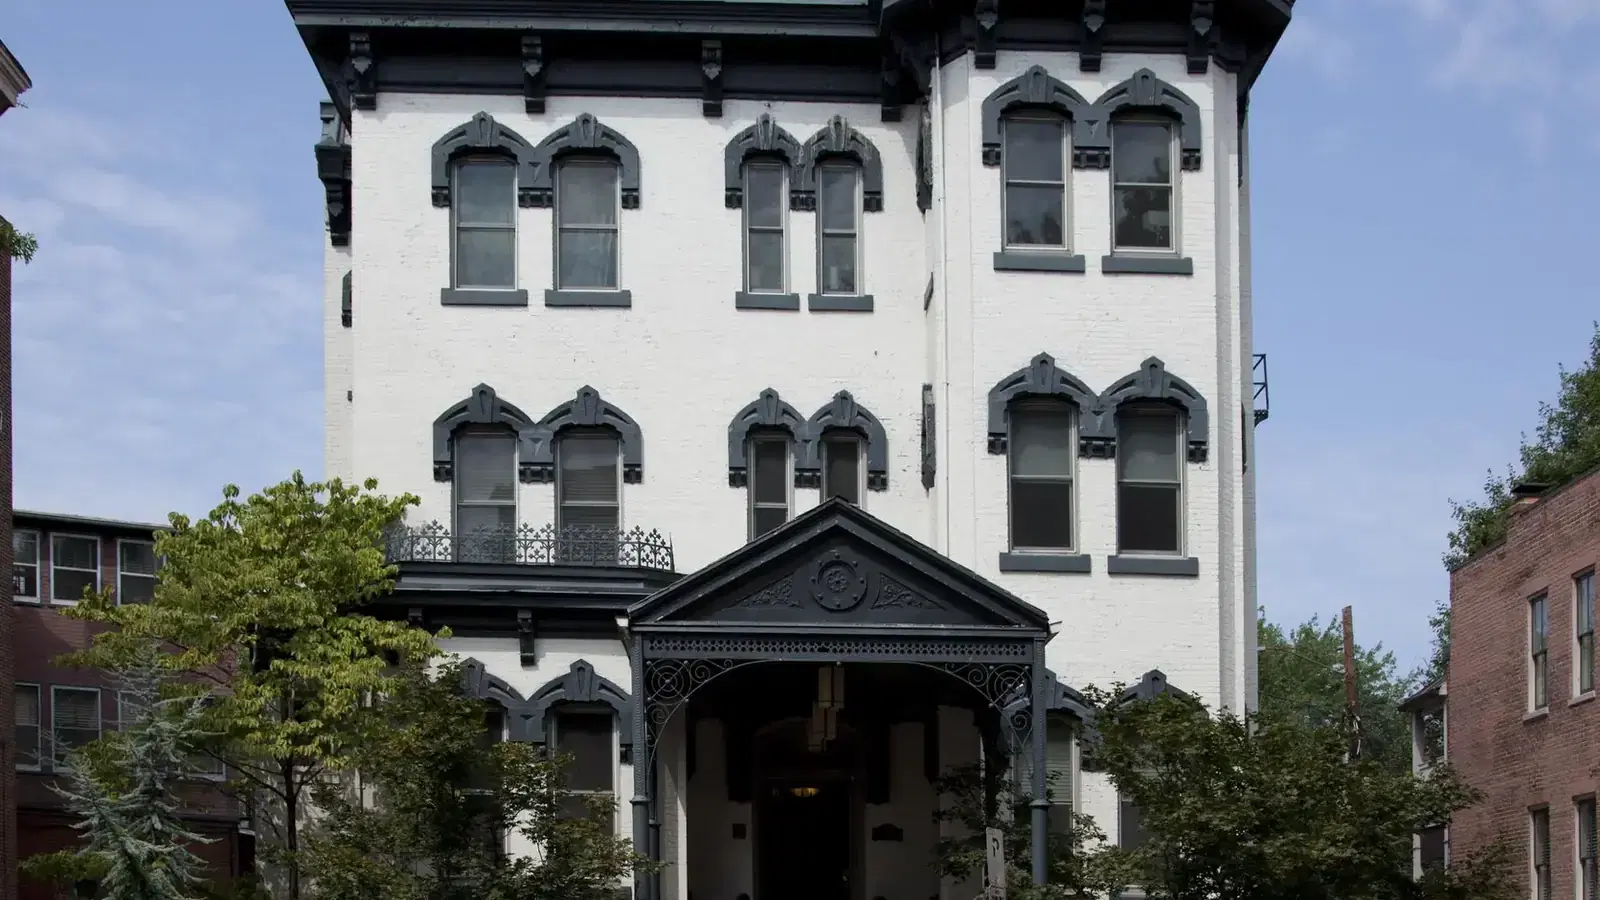 Logan Circle
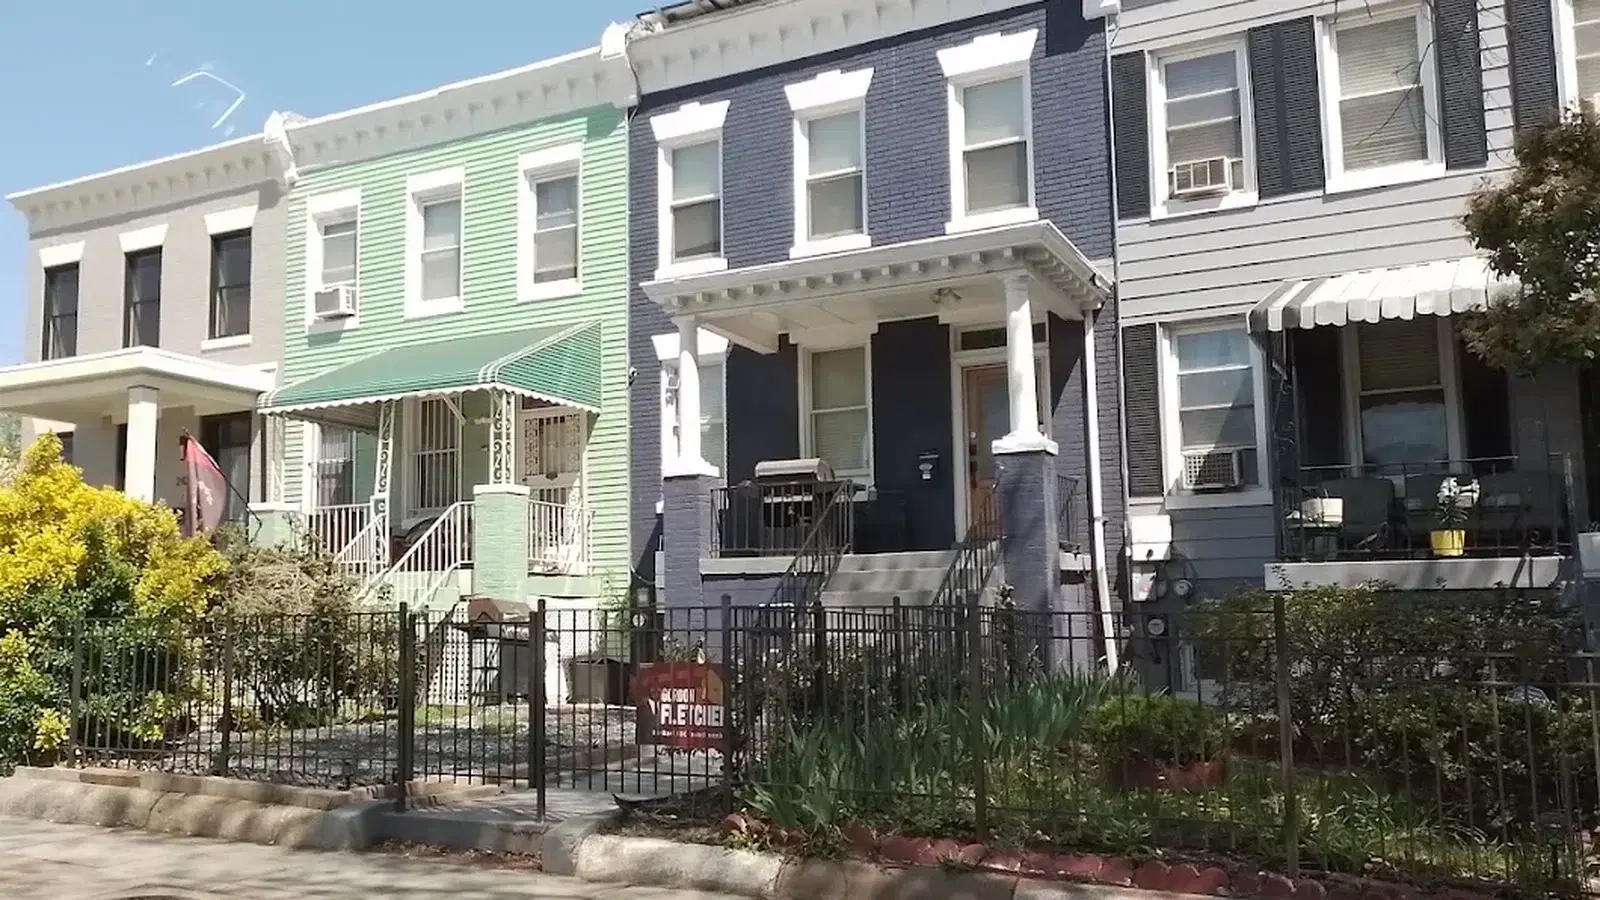 Petworth
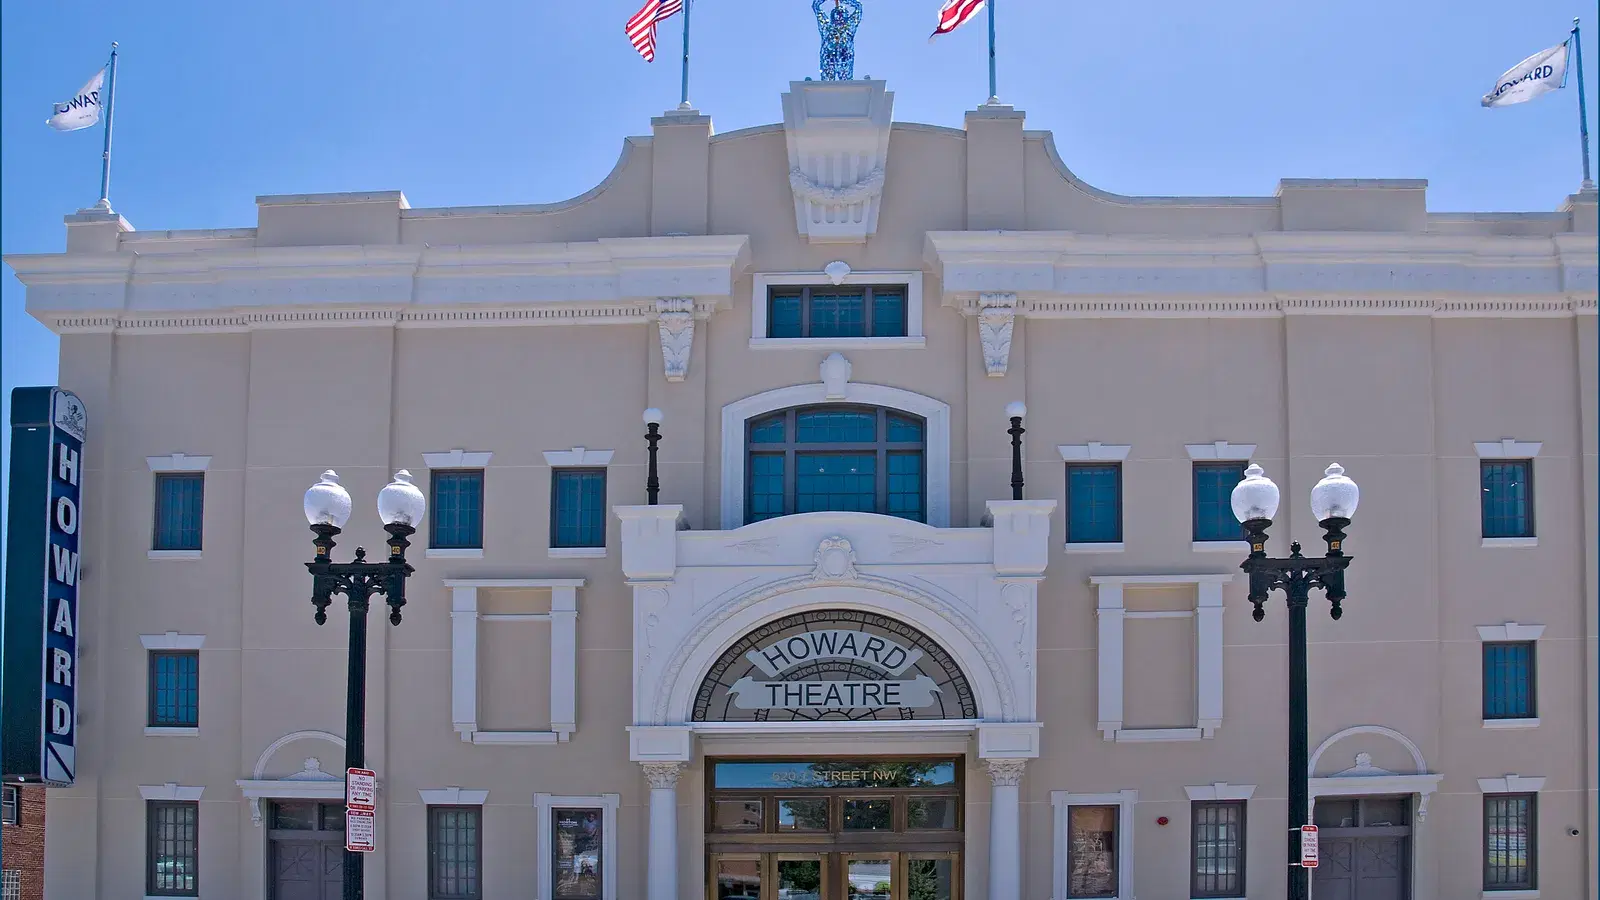 Shaw & U Street
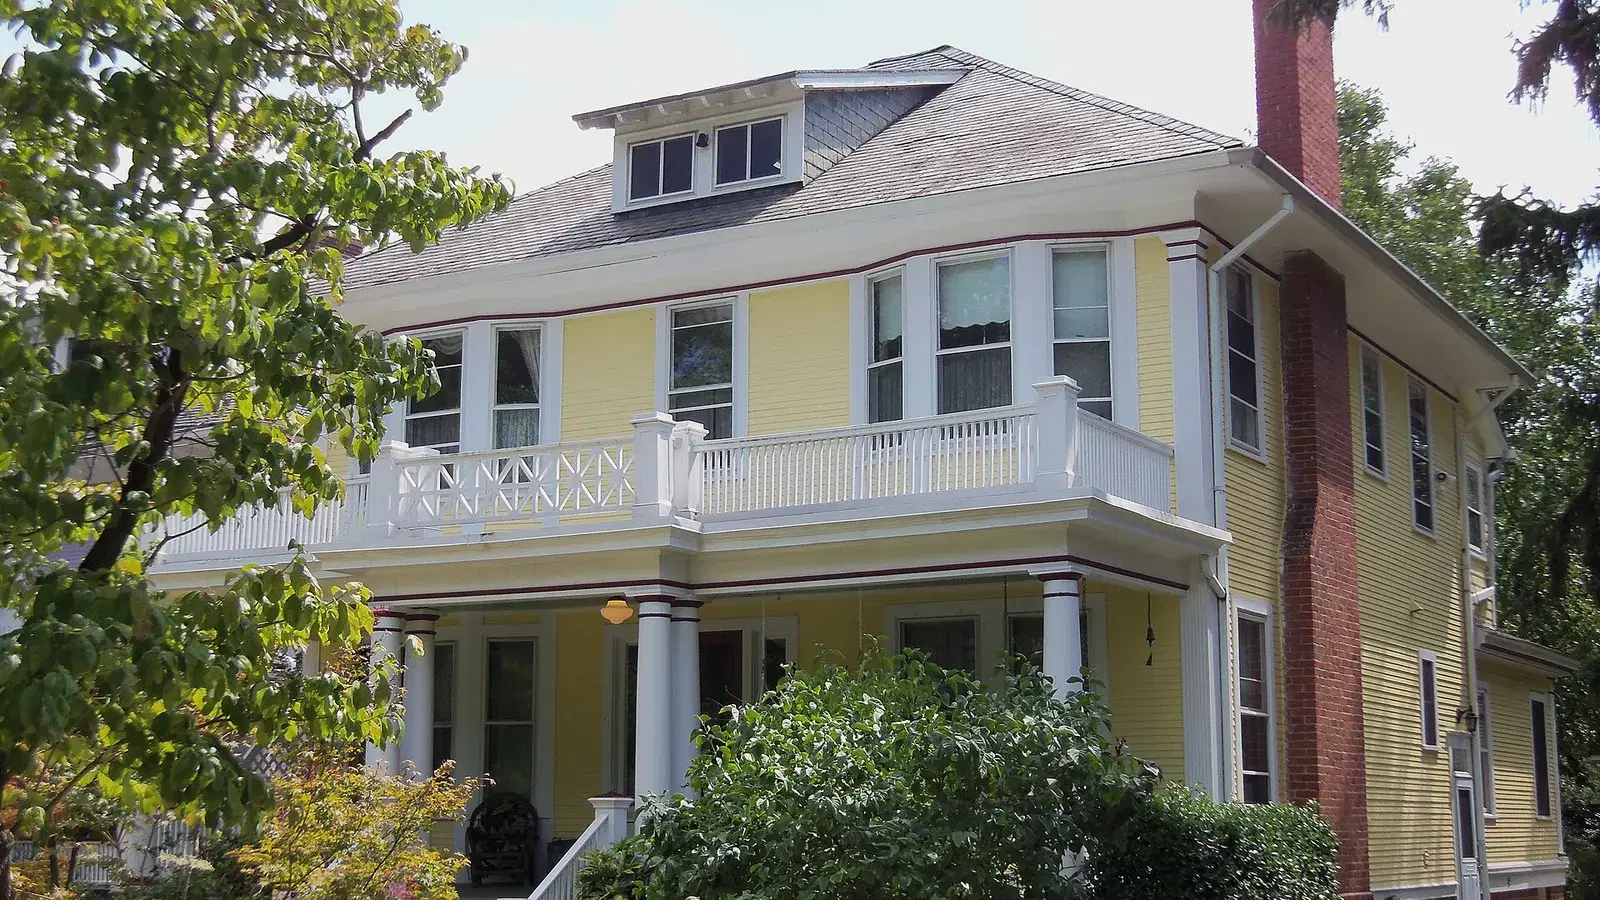 Takoma & Shepherd Park
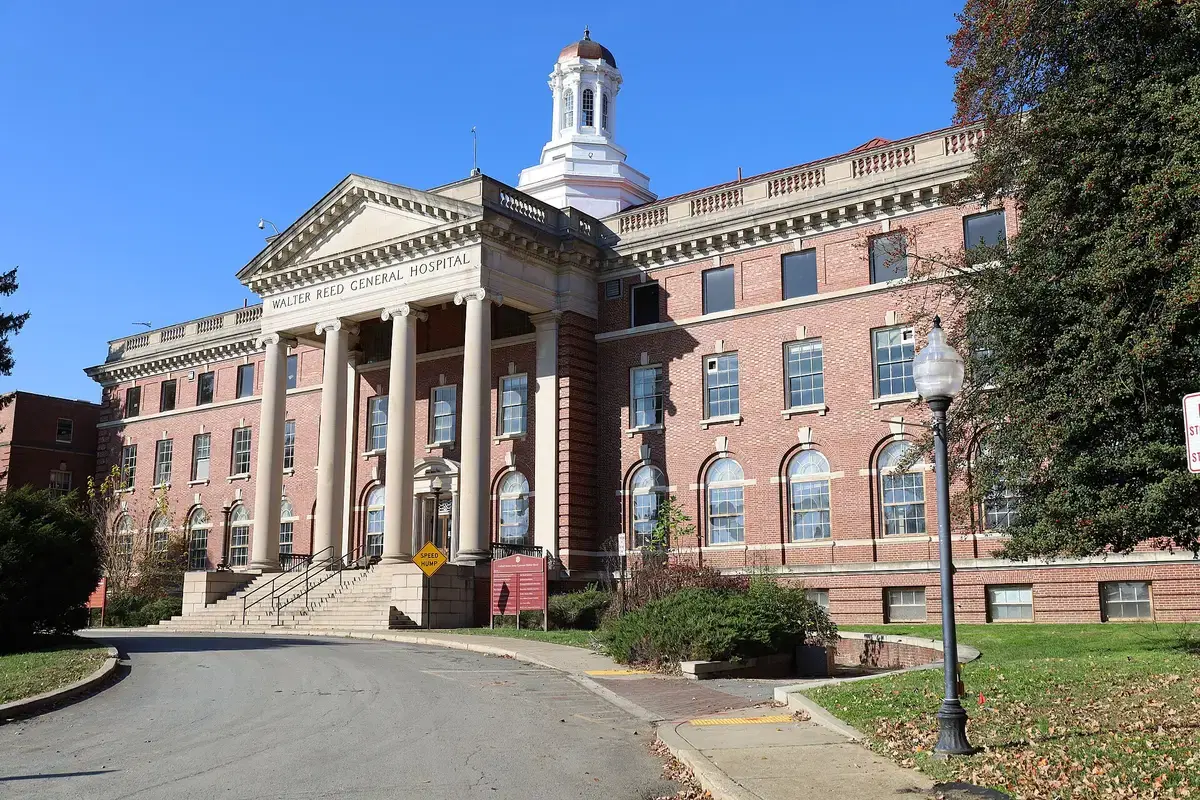 The Parks at Walter Reed
 Woodley Park
 Brookland
 Deanwood
 NoMa
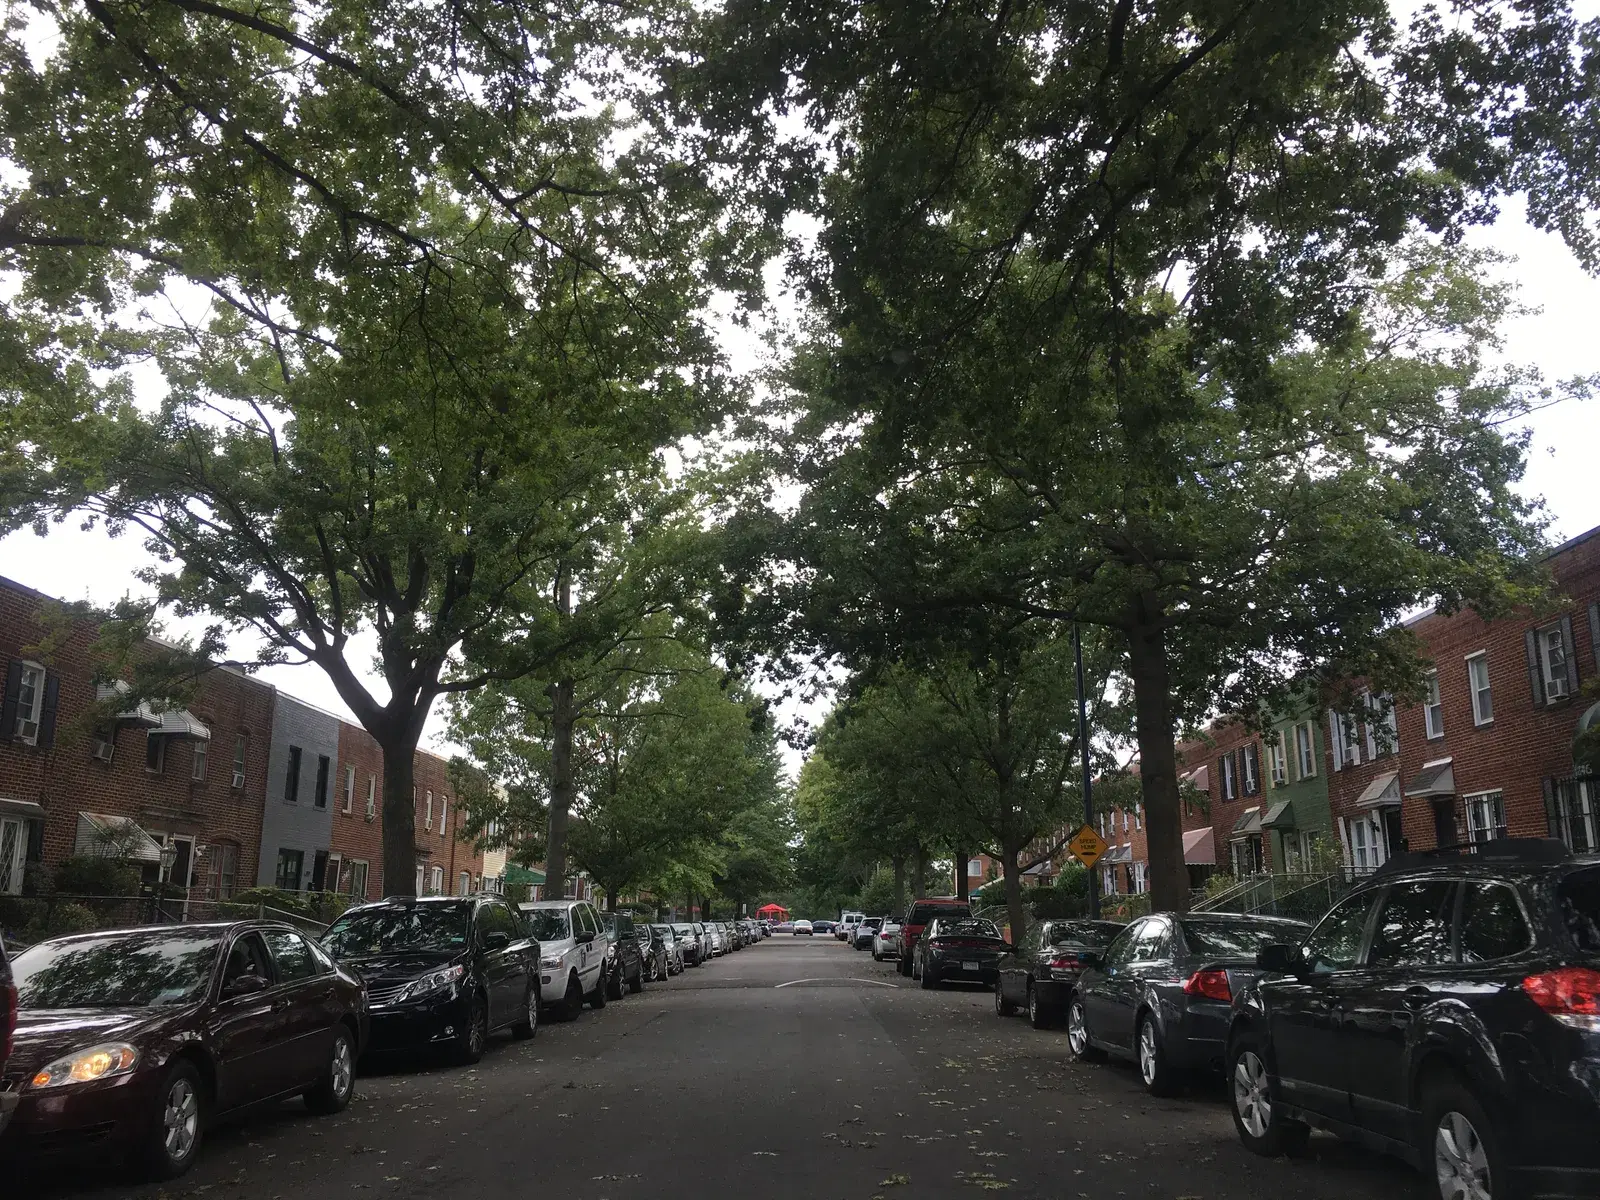 River Terrace & Benning
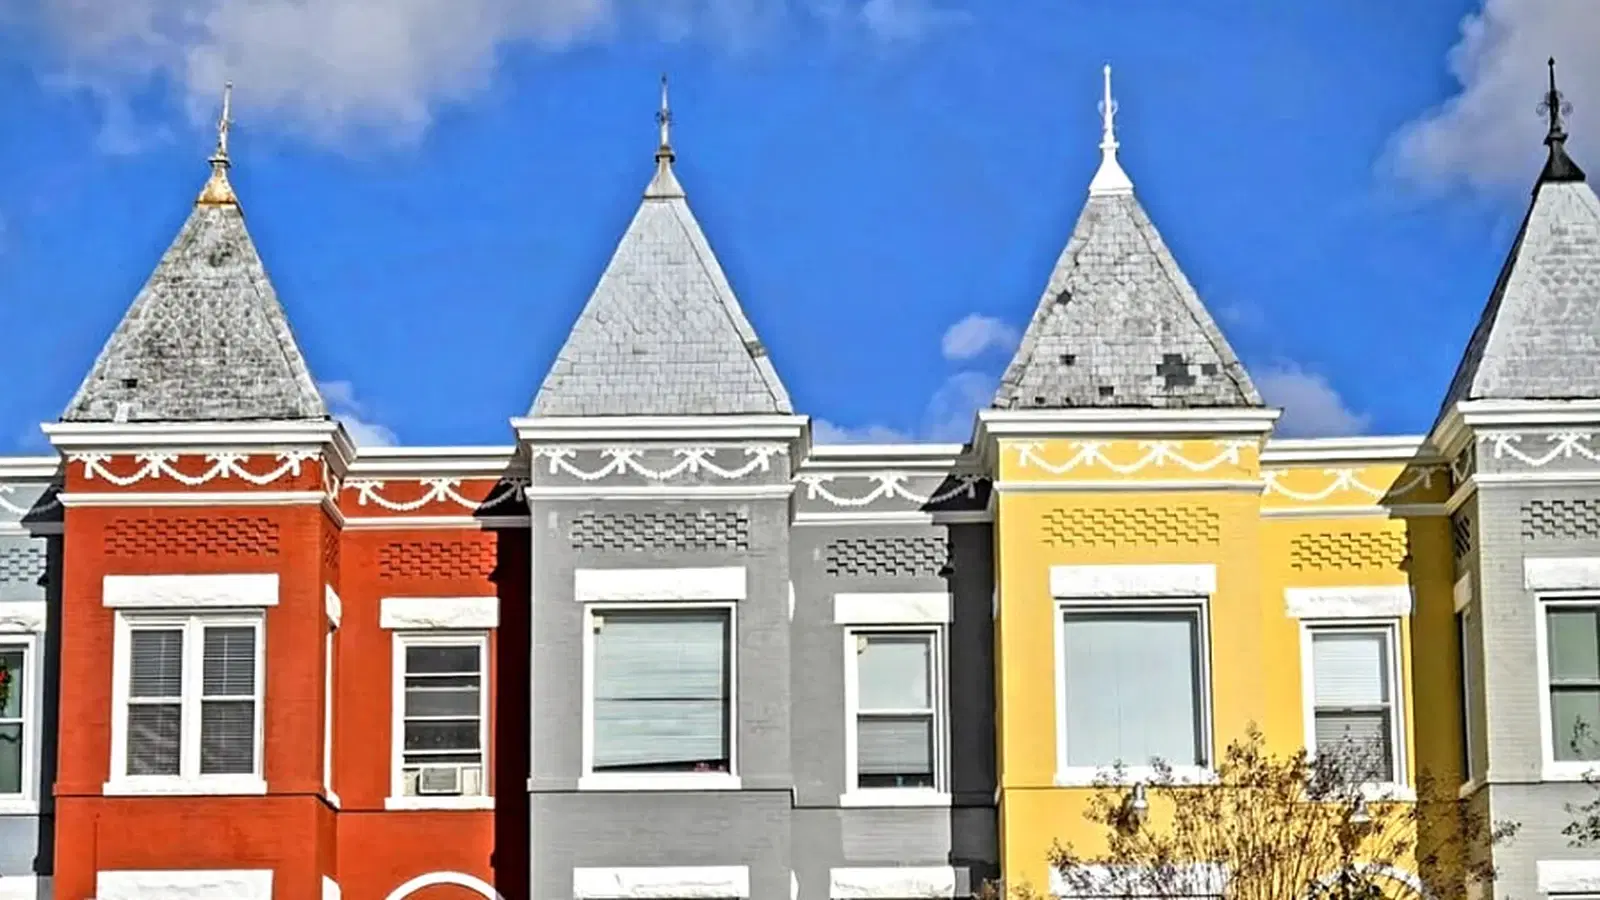 Trinidad & H Street
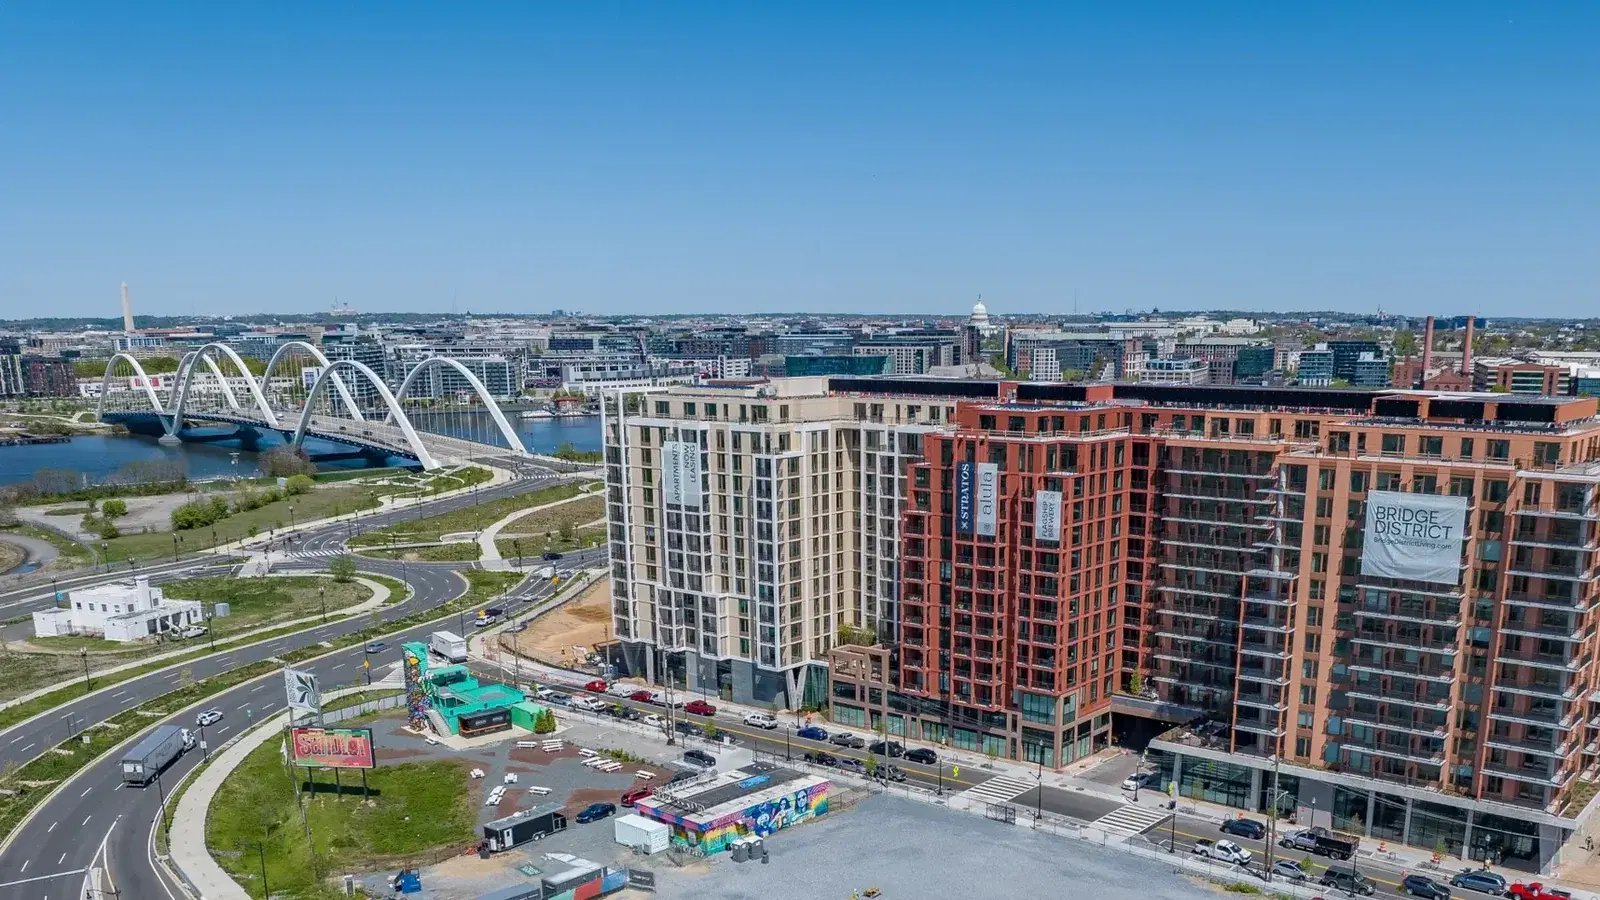 Bridge District
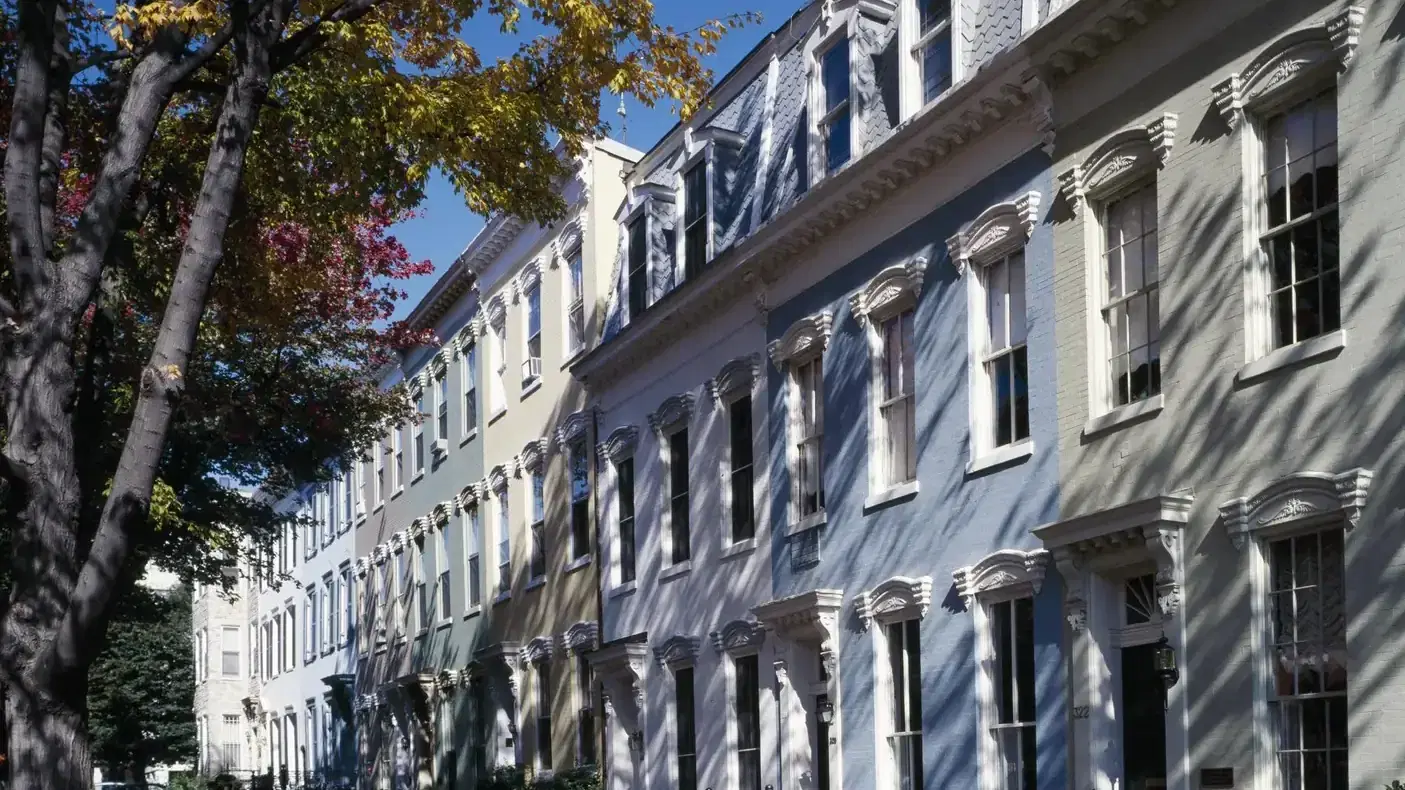 Capitol Hill
 Capitol Hill East
 Congress Heights
 Fairlawn
 Hillcrest & Fort Dupont
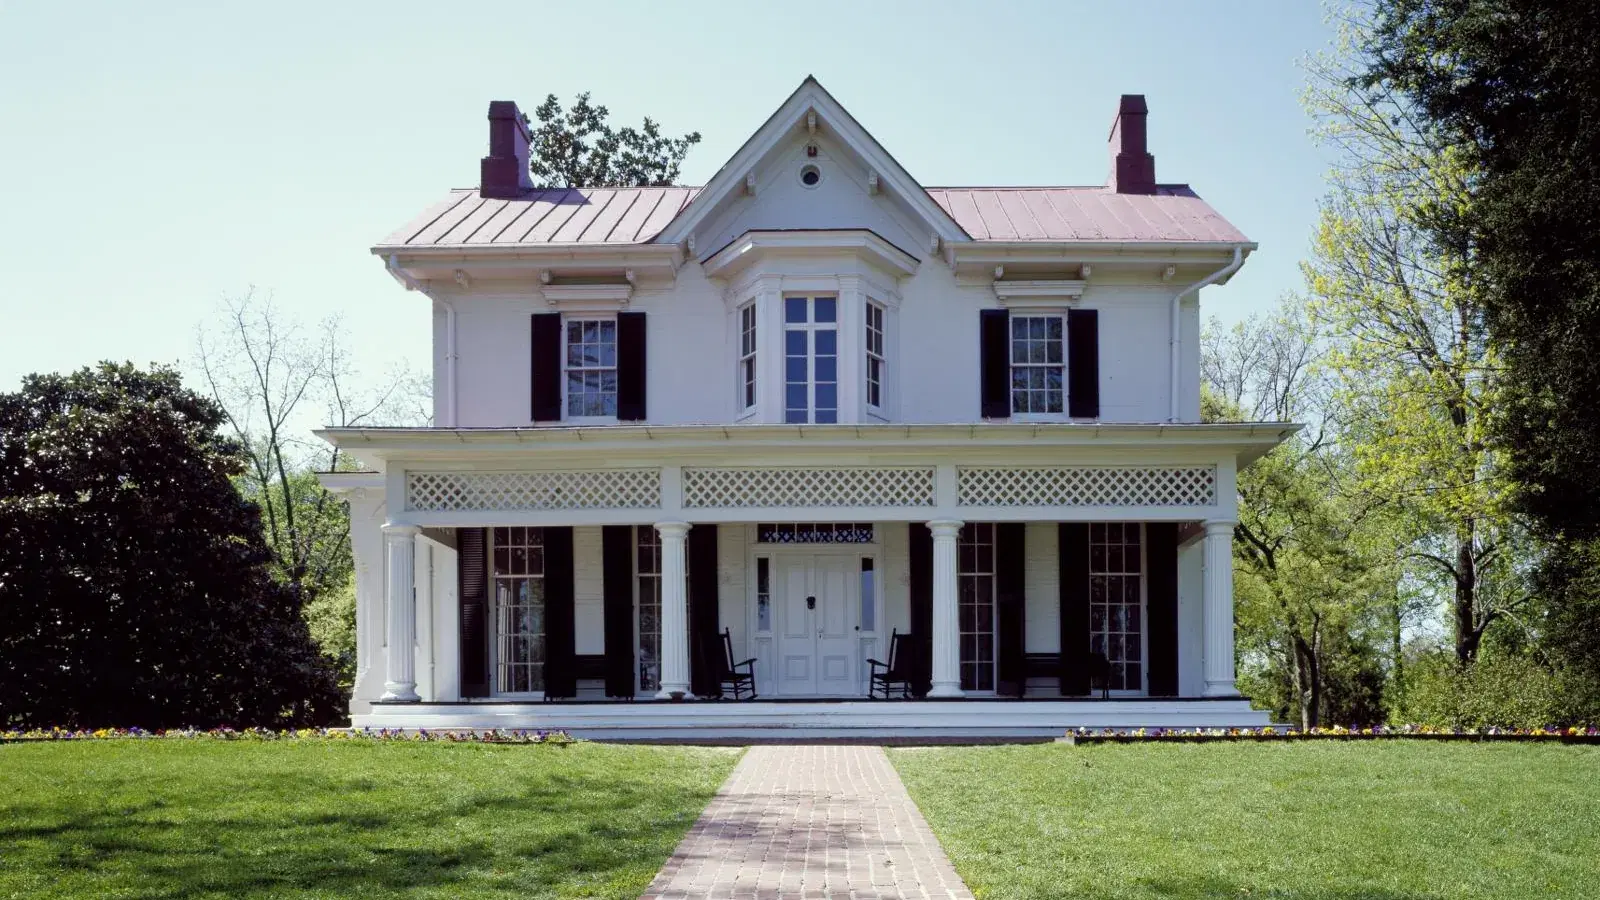 Historic Anacostia
 Marshall Heights & Benning Ridge
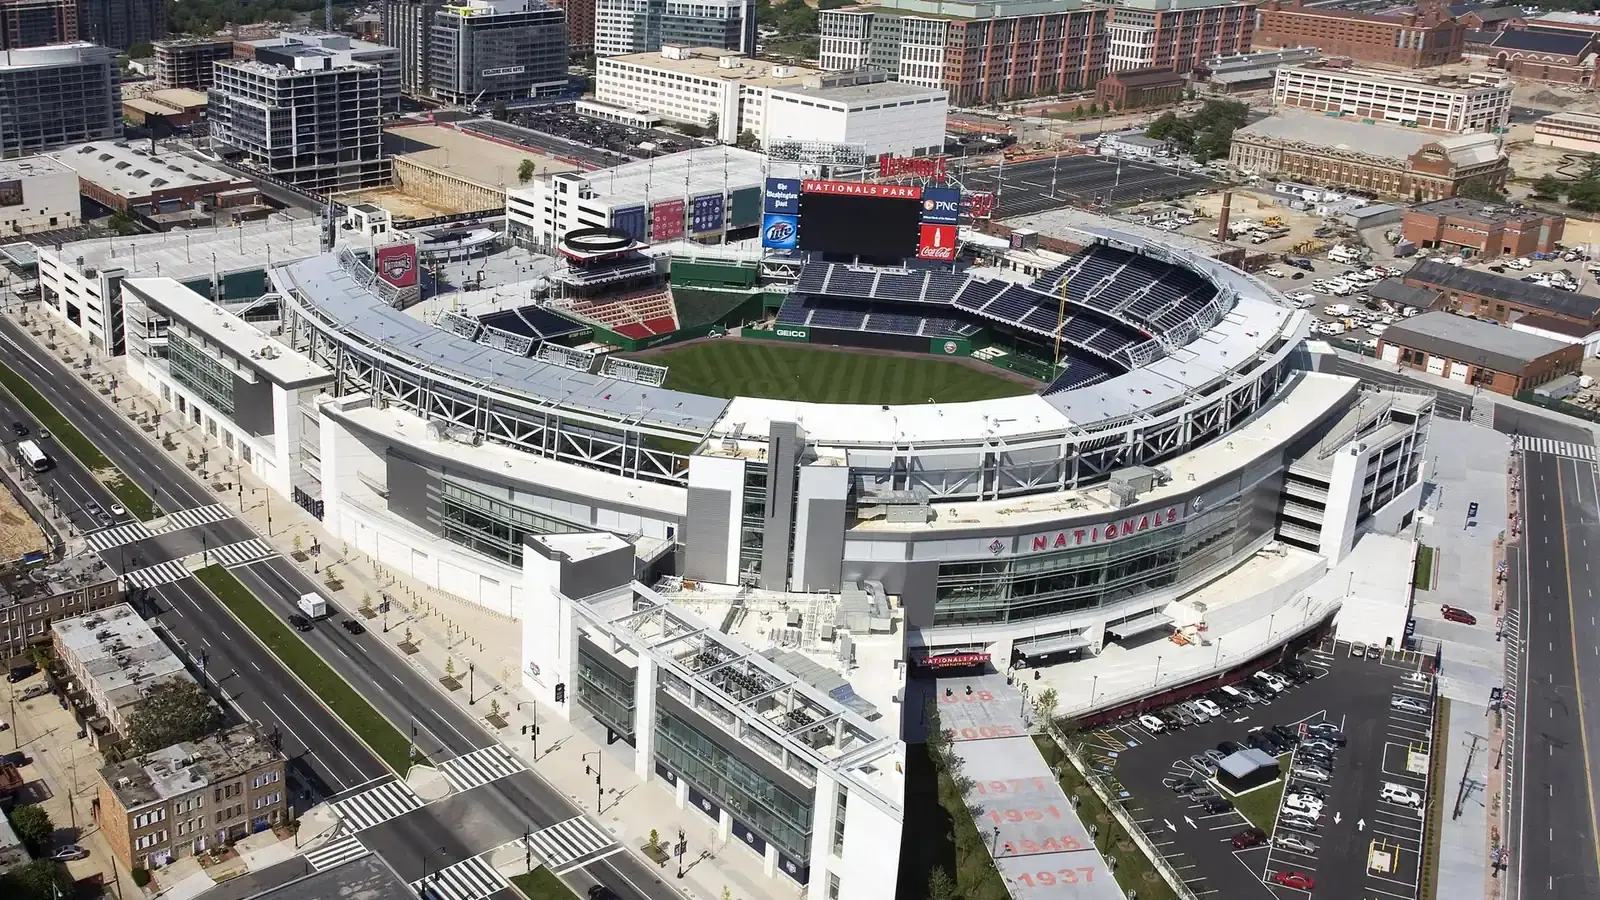 Navy Yard
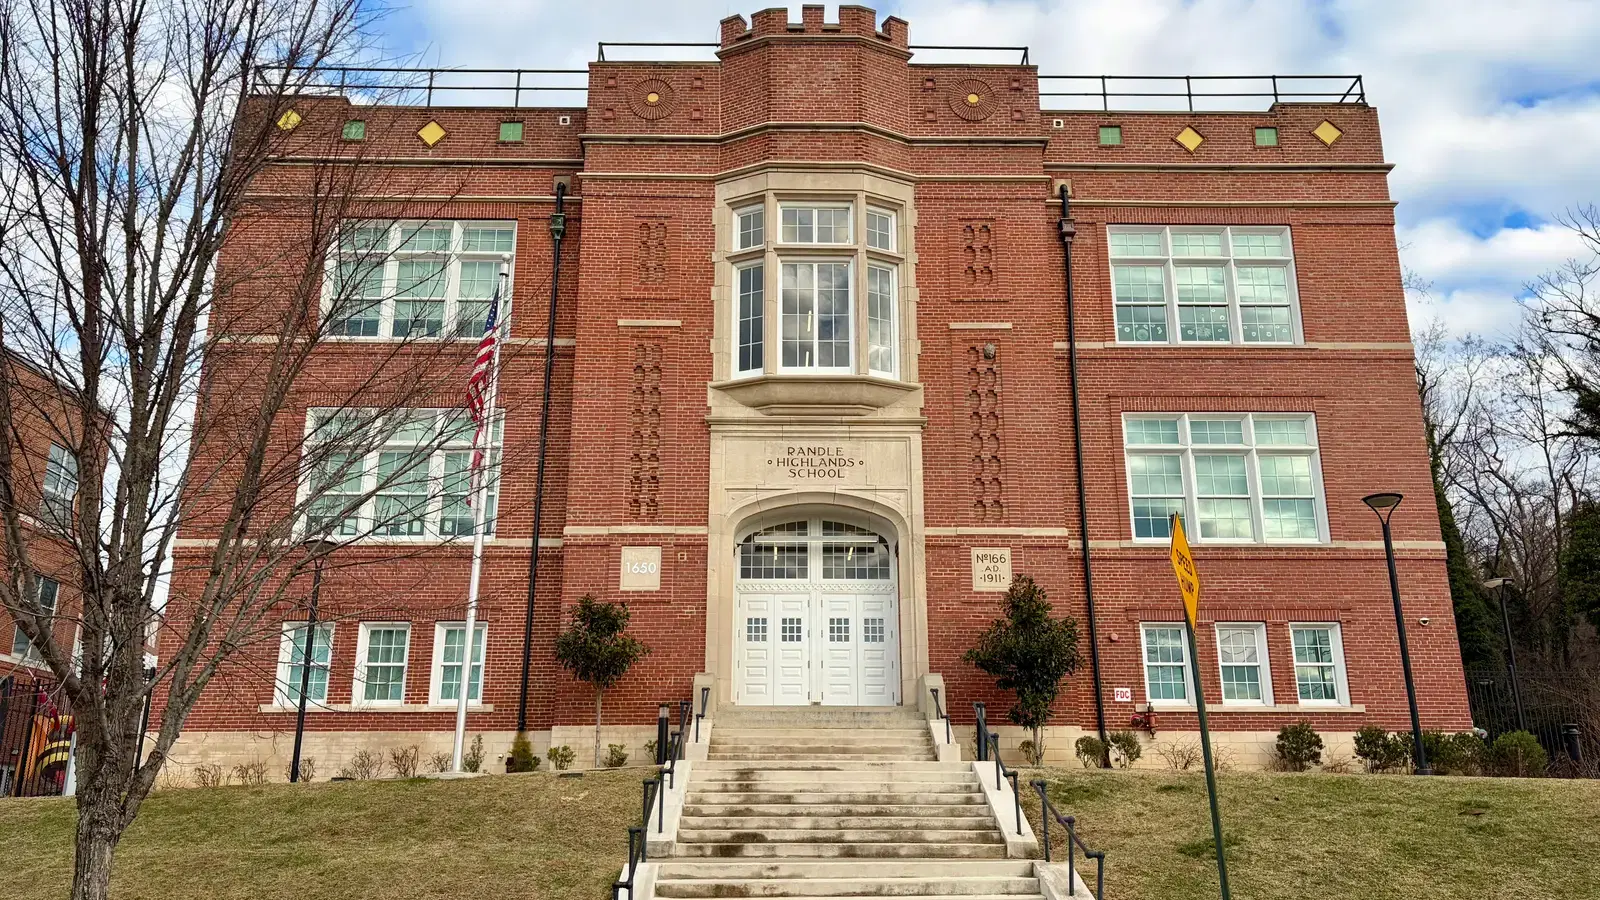 Randle Highlands
 St. Elizabeths East
 SW Waterfront & The Wharf
Loan programs
Purchase loan programs
Who each program fits and what sets it apart.
| Program | Who it fits | What sets it apart |
|---|---|---|
| Conventional → | Most buyers, for condos, rowhouses and detached houses. | The standard Fannie Mae and Freddie Mac loan. You can ask to drop mortgage insurance once you reach 20% equity. |
| FHA → | Buyers whose down payment comes as a gift from family, or whose credit is still building. | Insured by the FHA. Condos need an FHA-approved building or single-unit approval. |
| VA → | Veterans, active-duty service members and eligible surviving spouses. | Guaranteed by the Department of Veterans Affairs. No monthly mortgage insurance. |
| Jumbo → | Loan amounts above DC's 2026 limit of $1,249,125. | Fixed and adjustable terms. |
| Doctor Loan → | Physicians, dentists and other doctoral-level clinicians, including residents and fellows. | No mortgage insurance, 680 minimum credit score, loan amounts up to $2 million. Primary residence only. |
- Conventional →
Most buyers, for condos, rowhouses and detached houses.
The standard Fannie Mae and Freddie Mac loan. You can ask to drop mortgage insurance once you reach 20% equity.
- FHA →
Buyers whose down payment comes as a gift from family, or whose credit is still building.
Insured by the FHA. Condos need an FHA-approved building or single-unit approval.
- VA →
Veterans, active-duty service members and eligible surviving spouses.
Guaranteed by the Department of Veterans Affairs. No monthly mortgage insurance.
- Jumbo →
Loan amounts above DC's 2026 limit of $1,249,125.
Fixed and adjustable terms.
- Doctor Loan →
Physicians, dentists and other doctoral-level clinicians, including residents and fellows.
No mortgage insurance, 680 minimum credit score, loan amounts up to $2 million. Primary residence only.
Not sure which fits? Get pre-qualified and your loan officer will recommend one.
Refinancing a home you ownRefinance to change your rate or term, or take cash out.Refinance options →Ask a question
A licensed DC loan officer will answer your question by email within one business day.
Get pre-qualified for a DC home purchase
Answer five questions and a licensed loan officer will text or call within the next business hour. No credit pull.